
Is your approval process still doing what you think it does?
Whilst most invoice, expense and purchasing card processes are put in place to provide appropriate checks and controls, once they are up and running, they are not always reviewed as regularly as they perhaps should be.
Over time, new software, changes in staff and small changes to the way people work can mean the process being followed day to day is quite different from the one set out in your policy – creating gaps in your controls that can easily be missed.
Who should review your approval controls?
Anyone involved in approving supplier invoices, staff expenses or purchasing card statements should understand how the process works in practice, however, responsibility for reviewing approval controls should sit with someone who has enough oversight of the process to identify where it may no longer be working as intended.
This will often be a finance director, financial controller or senior finance manager, depending on the size of the business.
The person carrying out the review should also be sufficiently independent from the day-to-day approval process to give it an objective assessment.
Why do approval controls change over time?
Even well-designed controls can change as the business and its processes change.
For example:
- A colleague covers for someone on leave and misses a step in the process.
- A new finance system changes how receipts or supporting documents are stored.
- A regular supplier’s invoices start being approved without the same level of review.
- Staff become used to taking shortcuts to save time.
Individually, these changes may not seem significant. But over time, they can leave you with a process that looks effective on paper but works differently in practice.
What should an internal audit review of your approval processes cover?
An internal audit review should look at whether your approval processes are working as intended, both on paper and in practice.
This could include:
- Whether invoices are approved by the right people and within agreed limits
- Whether there is sufficient supporting evidence before an invoice is approved
- Whether expenses are checked against your expenses policy
- Whether purchasing card transactions are properly reviewed and reconciled
- Whether approval controls can be bypassed or overridden
- Whether responsibilities and approval limits are clearly defined
- Whether controls are being followed consistently across the business
Reviewing these areas can help identify gaps between your documented processes and what is actually happening day to day.
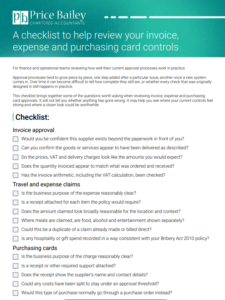
Download our invoice, expense and purchasing cards checklist here...
A starting point for reviewing your controls
We’ve put together a short, practical checklist covering invoice approval, expense claims and purchasing cards.
It is designed to help you review your current processes and identify areas that may need a closer look.
If the checklist highlights any gaps, a more detailed review may be worthwhile. The Price Bailey Internal Audit team can help you assess your approval processes, identify weaknesses and recommend practical improvements.
We always recommend that you seek advice from a suitably qualified adviser before taking any action. The information on this page is intended as a general guide only. While we work to keep our content accurate and up to date, we cannot guarantee that it reflects the position at the time you are reading it. No responsibility for loss occasioned by any person acting or refraining from action as a result of this material can be accepted by the authors or the firm. For more information on our editorial process, click here.
Sign up to receive exclusive business insights
Join our community of industry leaders and receive exclusive reports, early event access, and expert advice to stay ahead – all delivered straight to your inbox.
Have a question for our Internal Audit team? Contact us below...
We can help
Contact us today to find out more about how we can help you