Contentious Tax Bulletin
Tax Investigations Partner, Andrew Park, provides a round up of the most recent and significant contentious tax news. Read more here...

Glossary
While the income statement reports profit and the balance sheet shows financial position at a point in time, the cash flow statement focuses solely on cash movements. It helps explain how a business generates cash, how that cash is used and whether sufficient liquidity is available to support day-to-day operations and future investment.
Cash flows are typically grouped into three categories. Operating activities relate to the core trading activities of the business. Investing activities include the purchase and disposal of long-term assets and investments. Financing activities cover transactions such as borrowing, loan repayments, share issues and dividend payments.
The cash flow statement is an important part of financial reporting under accounting frameworks such as FRS 102 and IFRS Accounting Standards, where applicable. It is also widely used by business owners, lenders and investors when assessing liquidity, financial resilience and the ability to generate cash over time.
A profitable manufacturing company invests heavily in new machinery during the year. Although it reports a healthy profit, the cash flow statement shows a significant cash outflow from investing activities, explaining why cash balances have reduced despite strong financial performance.
A cash flow statement reports the cash received and paid by a business during an accounting period, showing how its cash position has changed over time.
The statement is divided into operating activities, investing activities and financing activities, each reflecting a different source or use of cash.
It helps users understand a business’s liquidity, cash generation and ability to meet its financial obligations, providing information that cannot be obtained from profit figures alone.
An income statement reports income and expenses to calculate profit, while a cash flow statement reports actual cash movements regardless of when income or expenses are recognised.
Business owners, management teams, lenders, investors and other stakeholders use the statement to assess liquidity, funding requirements and overall financial resilience.
We always recommend that you seek advice from a suitably qualified adviser before taking any action. The information in this glossary entry only serves as a guide and no responsibility for loss occasioned by any person acting or refraining from action as a result of this material can be accepted by the authors or the firm.
Contact us today to find out more about how we can help you
Tax Investigations Partner, Andrew Park, provides a round up of the most recent and significant contentious tax news. Read more here...
HMRC's latest R&D tax credit statistics show £8.2bn claimed in 2024-25 despite fewer claims. See the key findings in our infographic.
This guide answers the questions landlords raise with us most often: how the Section 24 tax reducer is calculated, how much it costs at different levels of borrowing, which thresholds it can push you over, and what changes in 2027/28 in each part of the UK.
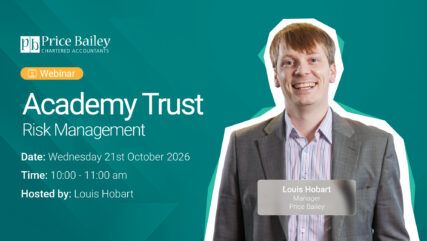
Join our webinar as we explore the evolving risk landscape facing academy trusts, key principles of risk management, and the top 10 questions every board should ask about risk.